Just six in 100 businesses ready for major changes to financial reporting
Date Posted: 6 Nov, 2026
Fewer than 6% of businesses have completed the implementation of revised FRS 102 requirements, a poll organised by UK top 10 accountancy firm Azets has revealed.
Key changes, including new lease accounting and a new five-step revenue recognition model, became effective for periods beginning on or after 1 January this year.
Therefore, they are first typically applicable for any businesses whose financial year end is 31 December 2026.
FRS 102 is the financial reporting standard applicable in the UK and Republic of Ireland which is regulated by the Financial Reporting Council (FRC).
The changes, which were announced in 2024, seek to align lease and revenue reporting more closely with the International Financial Reporting Standard, particularly IFRS 15 and IFRS 16.
Leases now need to be recognised on the balance sheet of a company and revenue recognition needs to make clear how and when bundled revenue arrangements from customer contracts are recognised.
The Azets poll, which followed a webinar on UK financial reporting standards, showed that 5.88% of respondents had completed their implementation of the revised FRS 102 requirements.
More than a quarter (27.6%) had not started yet, 36.5% were assessing the impact, 22.3% were currently implementing and just 7.6% were mostly implemented.
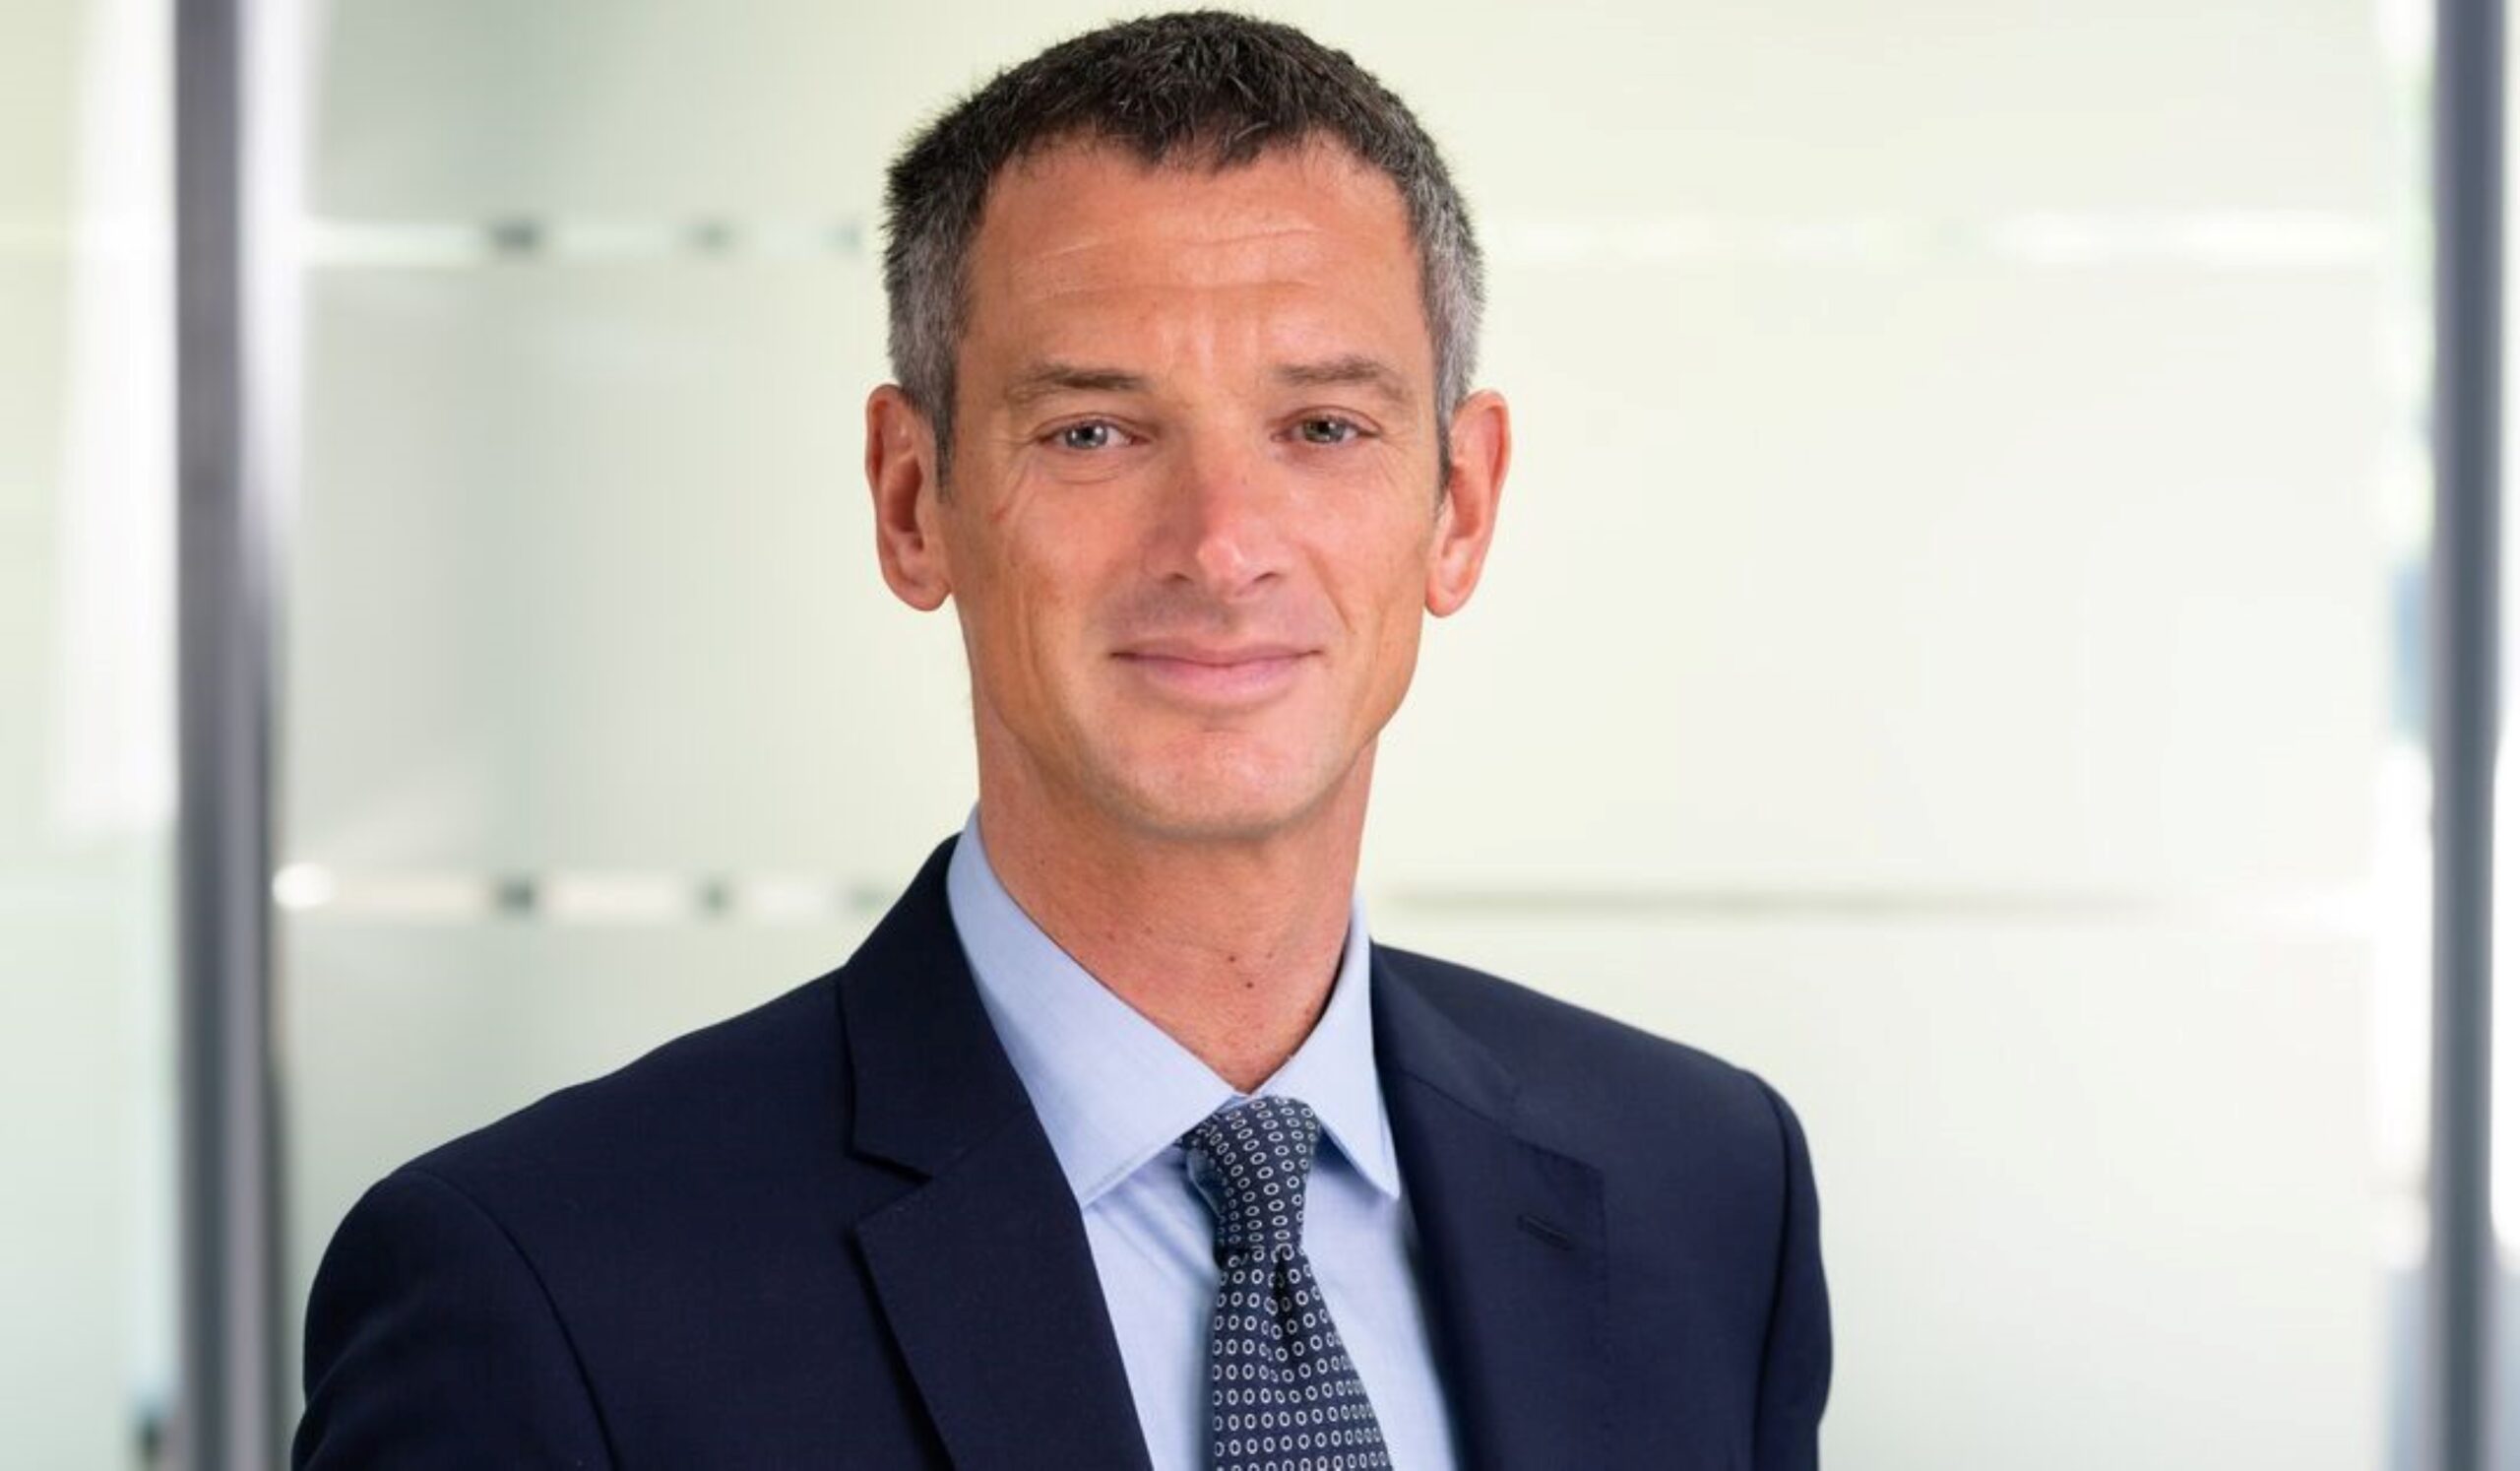
Greig McKnight (pictured), Regional Managing Director at Azets, said: “The 6% figure feels low, especially when you consider that 31 December is one of the most common financial year ends and many companies are about to end their first financial year end under the new requirements.
“I would urge businesses not to underestimate the time it can take to prepare. The actual calculations that go into the transition may not be overly complex, but a big part of the exercise is collating all the underlying documentation and ensuring everything has been appropriately considered.
“If a company has various different types of revenue streams and various customers with different terms, it can be a large exercise to go through all of those revenue contracts and arrange them into categories.
“Likewise, if a company has a large lease portfolio, has lease arrangements with non-simple terms, or does not have a readily available obtainable borrowing rate, the transition can create complexities.
“Overall, these changes are welcomed, as they should enhance the clarity and transparency of financial reporting, provide greater visibility over companies’ obligations and improve comparability between financial statements. This will benefit stakeholders, investors and suppliers in that they will be able to get a fairer picture of a company’s commitments and financial position.”
Becky Dawson, Technical Accounting Partner at Azets, said that while she could understand why the changes were needed for medium and large businesses, she admitted that it could feel disproportionate for particularly small businesses who were facing major upheaval to implement the requirements. “In these circumstances, proportionality and materiality must be considered,” she said.
Azets, the UK’s specialist business advisor to SMEs, which has its Scottish offices in Glasgow, Edinburgh, Aberdeen, Perth, Ayr and Inverness, posed two other questions in its webinar poll.
With regard to how confident organisations were that they would be ready for their next year-end reporting cycle under the revised requirements, 53.6% of respondents were fairly confident, 19.9% were unsure, 12% were very confident, 12% were slightly concerned and 2.4% were very concerned.
Regarding which area of the new UK GAAP (Generally Accepted Accounting Practice) changes would have the greatest impact on the business, 58% said lease accounting, 17.7% said revenue recognition, 16.7% said both and 7.6% said neither.